What defines the scope of the Student Enrollment Management Software Market?
The Student Enrollment Management Software Market comprises digital platforms designed to optimize recruitment, admissions, and retention workflows. Our research defines the scope across universities, K-12 institutions, and training centers. These systems are critical for modernizing administrative infrastructure, facilitating data-driven decision-making, and streamlining the student journey from initial inquiry to final graduation, ultimately serving as the backbone for institutional operational efficiency.
Structural Growth Drivers in the Student Enrollment Management Software Market
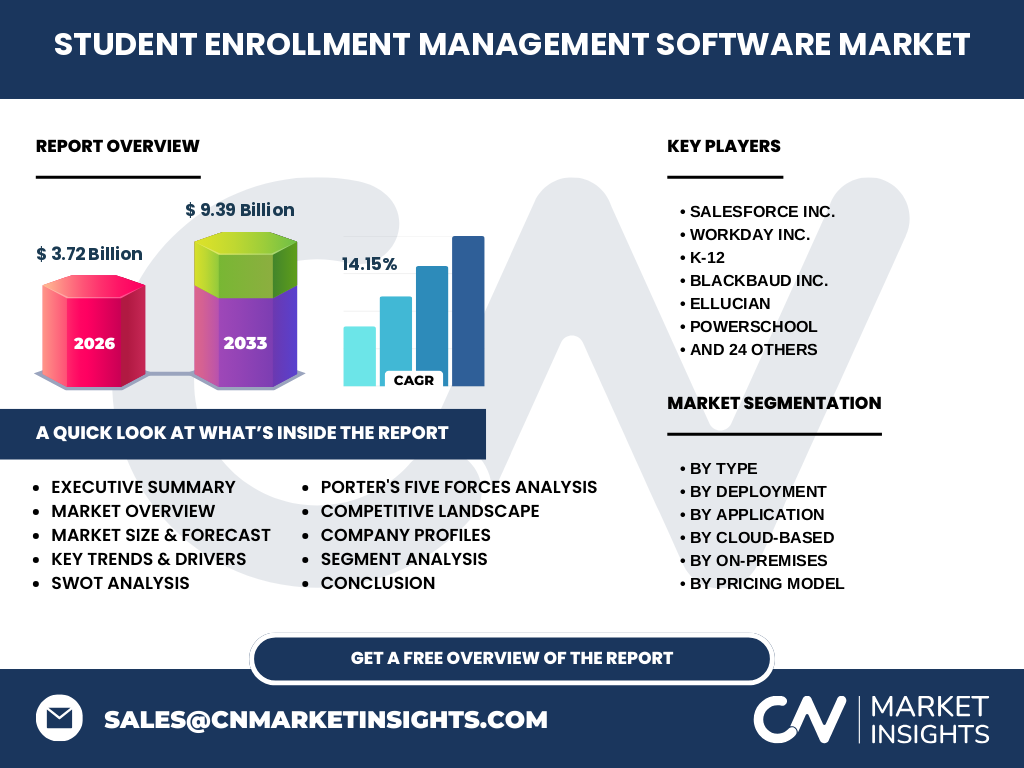
The market is bolstered by a CAGR of 14.15%, largely driven by the urgent need for institutions to manage complex digital admissions pipelines. Key growth drivers include the integration of SaaS-based automated workflows and the necessity for cross-departmental data synchronization. Conversely, high implementation costs and legacy integration hurdles serve as significant restraints, testing the agility of institutions when adopting next-generation administrative technologies.
Emerging Trends and Strategic Patterns
We observe a definitive shift toward AI-driven predictive analytics and mobile-first student engagement tools. Technolutions and AdmitHub inc. are pioneering conversational AI to reduce dropout rates during the enrollment cycle. These trends indicate that software is no longer just a database; it is a strategic asset for managing enrollment yield, personalization, and student retention in an increasingly competitive global education sector.
How did COVID-19 redefine industry recovery trajectories?
The pandemic served as a major catalyst, forcing an abrupt transition to remote-first enrollment operations. This necessitated immediate investments in cloud-native software to maintain continuity. Our analysis shows that this crisis permanently altered buyer behavior, prioritizing scalability and remote accessibility. The recovery phase is now characterized by long-term digital transformation strategies aimed at hardening institutional resilience against future logistical disruptions and fluctuating enrollment volumes.
Competitive Benchmarking and Strategic Dynamics
The competitive landscape is highly consolidated yet competitive, featuring giants like Salesforce Inc., Workday Inc., and Ellucian. These leaders leverage extensive ecosystems to dominate. Simultaneously, specialized innovators like TargetX and CampusLogic Inc. focus on high-touch CRM functions. The market concentration remains high, as institutions prefer vendors offering robust API integration capabilities to unify disparate campus software stacks.
Executive Summary of the Student Enrollment Management Software Market
With a projected valuation of 9.39 Billion by 2033, the market is poised for robust expansion. Our synthesis reveals that SaaS and cloud-based models are becoming the de facto industry standard over on-premises solutions. The intersection of rising administrative burdens and the need for personalized student engagement creates a high-growth environment, rewarding vendors who offer seamless, intuitive multi-channel communication suites.
Projected Growth from 2027 to 2033
From 2027 through 2033, the market is expected to surge from a solid baseline, culminating in a 9.39 Billion valuation. This growth trajectory reflects a compound annual growth rate of 14.15%. Our data suggests that accelerated institutional investments in lifecycle management tools will be the primary engine of this valuation increase, as schools seek to maximize student lifetime value and operational ROI.
Segmentation Analysis and Market Roles
Segmentation is broken down by deployment, type, and application. Cloud-based SaaS remains the dominant growth segment due to its lower barrier to entry. Key applications include universities and K-12 systems, while training institutions represent a niche but expanding market. Pricing models like subscription vs. one-time allow for flexible budgeting, directly influencing procurement cycles in public and private institutional settings.
Regional Market Performance and Geographic Distribution
North America retains the largest market share due to the concentration of major technology innovators and advanced higher education infrastructure. However, the Asia-Pacific region is exhibiting the fastest growth rate, driven by a massive influx in student enrollment numbers and the digitizing of training centers. Localized constraints, such as data sovereignty regulations, influence regional adoption patterns significantly.
In-depth Regional Review of Adoption Patterns
In North America, PowerSchool and Skyward Inc. dominate the K-12 sphere, while Europe focuses heavily on GDPR-compliant data portability. In contrast, Teachmint and regional innovators are revolutionizing the Indian and Southeast Asian markets by prioritizing low-bandwidth, mobile-first enrollment interfaces. Understanding these geographic nuances is vital for vendors aiming to penetrate high-growth emerging economies effectively.
Strategic Positioning of Leading Companies
Market participants are strategically diversifying: Blackbaud Inc. targets institutional fundraising and management, while Jenzabar Inc. focuses on mid-market higher education solutions. Kira Talent carves a niche in video assessment, and Symplicity Corporation emphasizes student employability. These profiles demonstrate that specialization in specific student lifecycle stages is the most effective defense against broad-platform commoditization by industry titans.
Porter's Five Forces Analysis
The threat of new entrants is moderate, mitigated by high switching costs and the complex regulatory requirements of education sectors. Bargaining power of buyers is increasing as institutions demand all-in-one unified systems. Competitive rivalry is intense, focused on cloud-native SaaS integration capabilities. This analysis indicates that established players must innovate rapidly to maintain their defensive competitive advantage.
SWOT Analysis of the Industry
Strengths: High sticky factor of cloud-based SaaS. Weaknesses: High initial integration friction. Opportunities: AI-driven student matching and personalized enrollment pathways. Threats: Increasing data security risks and tightening regulatory bodies' privacy mandates. Companies like SchoolMint Inc. and FileInvite are successfully addressing these threats through enhanced security protocols and user-friendly document processing.
Value Chain Analysis
The value chain begins with R&D and software architecture design, moving through API-integrated development, and concluding with end-user implementation in schools and universities. Managed service providers play a critical role in bridging the gap between raw platform code and institutional administrative requirements. This structure highlights that value is increasingly captured at the post-installation support and customization layer.
Investment Insights and High-Potential Areas
We recommend focusing capital on AI-native enrollment tools and integrated compliance-management platforms. High-potential areas include SaaS products that bridge the gap between K-12 and tertiary education. Our research indicates that companies with robust API ecosystems—allowing for seamless communication with legacy Student Information Systems (SIS)—will command the highest valuation multiples during the upcoming 2027-2033 cycle.
Conclusion and Key Takeaways
The Student Enrollment Management Software Market is fundamentally transitioning from static record-keeping to dynamic student lifecycle management. With a forecast of 9.39 Billion, the sector offers significant growth. Institutional leaders should prioritize flexible, cloud-based architectures. The ultimate takeaway is that success hinges on data-centric engagement, as institutions compete globally for qualified student cohorts.
Research Methodology for Baseline Estimates
Our estimates are triangulated using a blend of primary stakeholder interviews with institutional CIOs, analysis of trade registry data, and secondary macroeconomic indicators. We normalize growth patterns against historical SaaS adoption rates and regional education spending trends to ensure accuracy. This robust methodology allows us to maintain a high degree of confidence in our 14.15% CAGR projection.
Scope and Coverage Limitations
This report covers the global market for enrollment management solutions across K-12, higher education, and vocational training sectors. The scope is limited to digital software platforms, excluding physical hardware or unrelated administrative infrastructure. While our analysis is comprehensive, it accounts for localized regulatory variations, which may impact exact market penetration rates in highly restricted geographical regions.
Recent Developments and Market Announcements
Recent activity highlights a flurry of strategic M&A and modular product launches. Companies like Foundant Technologies have expanded their footprint, while Snowman Software continues to innovate in the K-12 space. Partnerships between CRM giants and specialized enrollment startups are becoming common, signaling a shift toward ecosystem-led growth rather than standalone product reliance in the current competitive market environment.